Mortgaged Missions: The Debt Arrangements Binding American Congregations to Their Lenders
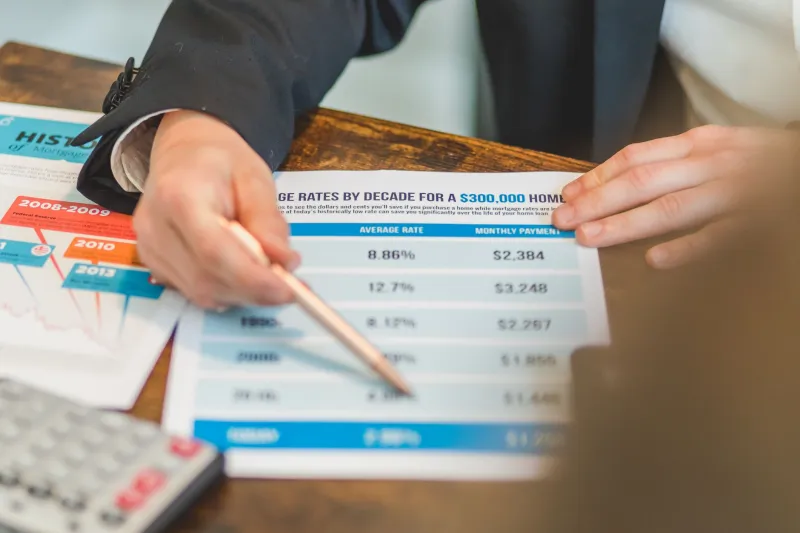
The construction loan that a mid-sized Pentecostal congregation in rural Mississippi signed in 2019 appeared, on its face, to be a straightforward instrument for financing a new sanctuary. The interest rate was above market but not dramatically so. The repayment schedule was structured across fifteen years. What the congregation's leadership — none of whom had formal financial training — did not fully grasp at signing was a clause requiring the entire principal to be renegotiated at the five-year mark, at terms to be set by the lender.
When that renegotiation arrived in 2024, the lender — a faith-affiliated real estate finance company operating across the Southeast — presented revised terms that increased the effective interest rate by nearly four percentage points. The congregation, which had already invested its reserves in the completed building and had no realistic exit option, accepted the new terms. Its monthly debt service now consumes approximately thirty-eight percent of total weekly giving.
This congregation's experience is neither unique nor extreme by the standards of what has become a substantial and largely unregulated sector of American religious finance.
A Market Built on Mission Language
The faith-based lending industry occupies a peculiar regulatory position. Because the primary borrowers are religious organizations rather than individual consumers, the federal statutes that govern predatory lending in residential and small-business contexts — the Truth in Lending Act, the Home Ownership and Equity Protection Act, and various state-level consumer protection frameworks — apply with limited force or do not apply at all.
Lenders operating in this space have developed a distinctive market identity. Many present themselves as ministry partners rather than financial institutions, emphasizing shared values and a commitment to the growth of faith communities. Marketing materials reviewed by Religious Intelligence routinely invoke stewardship theology — the idea that faithful management of material resources is itself a spiritual discipline — to frame debt acquisition as an act of communal vision rather than financial risk.
The organizations providing this financing range from dedicated religious lending institutions, some of which hold formal nonprofit status, to subsidiary arms of larger commercial banks that have identified faith communities as an underserved and relatively stable borrower category. In between sits a network of brokers, consultants, and faith-based real estate developers whose compensation structures create strong incentives to close transactions regardless of whether the underlying debt is sustainable for the borrowing congregation.
The Structural Features of Concern
Financial analysts and consumer advocates who reviewed loan documents obtained by Religious Intelligence identified several recurring structural features that they characterized as inconsistent with responsible lending practice.
Balloon payment provisions — in which a large portion of the principal becomes due at a fixed future date, regardless of the borrower's payment history — appeared in a majority of the instruments examined. These provisions are particularly consequential for congregations, whose revenue streams are inherently variable and whose membership demographics can shift substantially over a five-to-ten-year horizon.
Cross-collateralization clauses, which allow a lender to claim multiple properties as security for a single loan, were present in roughly a third of the documents reviewed. For a congregation that owns both a sanctuary and an adjacent community facility, such a clause means that a default on one loan can trigger a claim against assets that were not the original subject of the financing.
Prepayment penalties, which charge borrowers a fee for retiring debt ahead of schedule, were nearly universal. These provisions effectively trap congregations in their loan terms even when improved financial circumstances might otherwise allow them to refinance at better rates.
Who Bears the Risk
The communities most exposed to these arrangements are predictable. Rural congregations, predominantly Black churches in historically underinvested urban neighborhoods, and first-generation immigrant faith communities frequently lack access to the financial counsel that would allow them to evaluate complex loan instruments before signing. Several pastors interviewed for this analysis described receiving legal review of loan documents from attorneys recommended by the lender itself — a conflict of interest that would be impermissible in regulated consumer finance contexts.
The consequences of unsustainable debt extend well beyond balance sheets. A congregation consuming a disproportionate share of its giving in debt service has fewer resources for the pastoral staff, community programming, and outreach activities that define its public mission. When financial pressure becomes acute, governance structures tend to concentrate authority in the hands of whoever manages the lender relationship — often a senior pastor or a small board of trustees — at the expense of broader congregational accountability.
Several cases reviewed in this analysis involved congregations that ultimately lost their physical properties through foreclosure or distressed sale. In at least two instances, the acquiring party in the distressed sale was a real estate entity with documented prior relationships with the original lender, raising questions about whether the lending arrangement had been structured from the outset with acquisition as an anticipated outcome.
The Regulatory Landscape and Its Limits
At the federal level, no agency currently exercises comprehensive supervisory authority over lenders whose primary clientele consists of religious organizations. The Consumer Financial Protection Bureau's jurisdiction is largely limited to consumer financial products. The Internal Revenue Service's oversight of religious nonprofits focuses on tax-exempt status rather than financial practices affecting third parties. State banking regulators vary considerably in their appetite and capacity to examine faith-affiliated lending entities, particularly those that are themselves organized as nonprofits.
Several legal scholars specializing in the intersection of religious liberty and financial regulation have argued that this gap is not accidental. Extending consumer protection frameworks to religious borrowers would require regulators to engage with the internal governance structures of faith organizations — a step that raises genuine First Amendment concerns and that legislators have historically been reluctant to take.
Advocacy organizations focused on community economic development have begun pressing for disclosure requirements that would stop well short of substantive regulation: mandating that faith-based lenders provide standardized cost-of-credit disclosures comparable to those required in consumer contexts, and requiring that borrowing congregations obtain independent legal counsel before closing. Neither proposal has advanced in any state legislature to date.
Until the regulatory framework catches up with the market, the debt arrangements binding American congregations to their lenders will continue to be written in language that the congregations themselves are often ill-equipped to read — and in terms that serve the interests of the parties who drafted them.